Showing posts with label long-only. Show all posts

Tuesday, 26 April 2011

Selecting the Best Managers – a natural bias to hedge fund managers?

I carried out manager research for an American fund of hedge funds for several years early last decade. Manager research and portfolio construction is a team effort so I had to find a way to put across to my colleagues the merits of the managers I followed. We use a lot of inputs to understand how managers manage capital, so in our heads each of us has a multi-faceted view of the portfolio manager and his process, but it is not feasible to put it all across to someone else. So we have to find ways to summarise and capture the essence of our take on the hedge fund manager.

In my case I used a numeric score of what I considered then, and still do now, the key drivers of performance. So I gave each manager a score between 1 and 10 for each of source of alpha and for risk management. Risk management included portfolio construction, position sizing, diversification, risk measurement, downside risk and use of stops. The source of alpha score took into consideration the added value of the specific person/people pulling the trigger, the breadth and depth of research, whether there was a unique or unusual information source being used, the sustainability of the manager's edge, how adaptable the approach was to change, and the richness of the opportunity set being addressed. A mid-ranking manager would score 6 for each, in the way I used the scales, but this was a closed marking system. No manager ever got 10 for either metric. I never gave any manager a score less than 4 for alpha or risk management in the time I carried out manager research. At the bottom end it is easy to understand why: managers setting up a hedge fund have nearly always has significant success previously in trading or investing. They are not neophytes; and though some learn on the job about managing capital in the hedge fund format, they have all managed capital before.

After a while meeting managers, and hearing how they do what they do, I realised that whilst the alpha score was important, risk management was a bigger differentiator. So getting into risk management issues early in the process saved a lot of time and effort: if a manager didn't have discipline and a consistent process in risk management it was time to move on to another hedge fund.

A legacy of this time is that I remain interested in how to assess managers – it is useful in my consultancy work, at the least. In the book I am reading at the moment – "Investing with the Grand Masters" by James Morton – I am engaged to see what criteria the author used for selection of the managers.

So I was interested to read about the Skandia Investment Group's Best Ideas fund range. Skandia has a fund platform and operates multi-manager funds, but the Best Ideas funds are not a standard fund of funds. Neither are they portfolios of pure hedge funds. These are portfolios of funds (mostly long-only funds) run by well-regarded portfolio managers who have been given the freedom to invest in their highest conviction investment ideas on a dedicated basis.


The lead manager on Skandia Investment Group's Best Ideas fund range, Lee Freeman-Shor, applies four key pieces of academic investment research to his selection process. These are:

1. High conviction investing: Research from Randy Cohen of the Harvard Business School, Christopher Polk and Bernhard Silli of the London School of Economics suggests that the bulk of fund manager's returns come from their highest conviction ideas. As a result the Best Ideas managers are limited to holding only ten stocks, their ten highest conviction ideas.

 2. Kelly Criterion: a formula first described in 1956 by John Larry Kelly to determine the optimal betting size to maximise wealth. Perhaps the most famous Kelly practitioner is Warren Buffet who once said: 'Why not invest your assets in the companies you really like? In 1972 Buffet had 42% of Berkshires assets in American Express. Freeman-Shor allows the managers to apply Kelly to the extent that they can invest up to 25% in a single stock.

3. High Active Share: this measures the proportion of a fund's assets that differ from the benchmark index. In their 2009 paper 'How Active is your fund manager? A new measure that predicts performance' Martijn Cremers and Anti Petajisto indicated that running a fund with a high 'active share' delivers the highest and most repeatable returns. The European Best Ideas Fund has a high active share, currently 83%.

4. Behavioural science: Research by Andrea Frazzini in 2006 showed that the best performing managers realise the highest proportion of losing trades. Freeman-Shor's job as overall portfolio manager is to be a coach and work with the Best Ideas managers to ensure they do not succumb to, amongst other things, sunken cost bias when they are losing and are thus executing their ideas appropriately.


In a good hedge fund there is a competition for capital between the investment ideas – that is, all full sized positions are conviction ideas. So the concept of high conviction investing is seen in the hedge fund world. The Kelly Criterion applies in several hedge fund strategies – event driven investing, activist investing, and to a lesser extent in global macro investing. The third piece of applied research might just say why hedge funds have inherent qualities relative to long only strategies, as 100% of many hedge fund portfolios are active bets. There are no index constraints in hedge fund portfolios, though the presence of positions held only to hedge impacts the percentage of the portfolio applied to seek alpha.

The fourth piece of academic research applied to the Skandia Best Ideas funds has a very strong resonance for me. The conclusion from Frazzini is that the best performing managers realise the highest proportion of losing trades. From my work with traders I know that this can be applied with minor tweaks in hedge funds: the best traders realise their losses either early, or in line with their stated stop-loss policies. This allows winners to run, and losers to be cut. This characteristic is also often seen in systematic approaches to markets, particularly by CTAs. With good money management it is feasible to run a successful CTA with a hit-rate (percentage of winning trades) of only 35%. The hit-rate in a discretionary money manager has to be a lot higher, and for a fundamentally driven manager with a long holding period the hit-rate can get into the high 80's as a percentage.

The fruit of the application of these concepts has been good – the Skandia European Best Ideas Fund has shown some strong out-perfromance. On the third anniversary since launch the fund was 17% ahead of the MSCI Europe index and 15% ahead of its peer group (Morningstar European Large Cap Blend), putting it in the top 5% of European funds since inception and 1st quartile over all time periods.

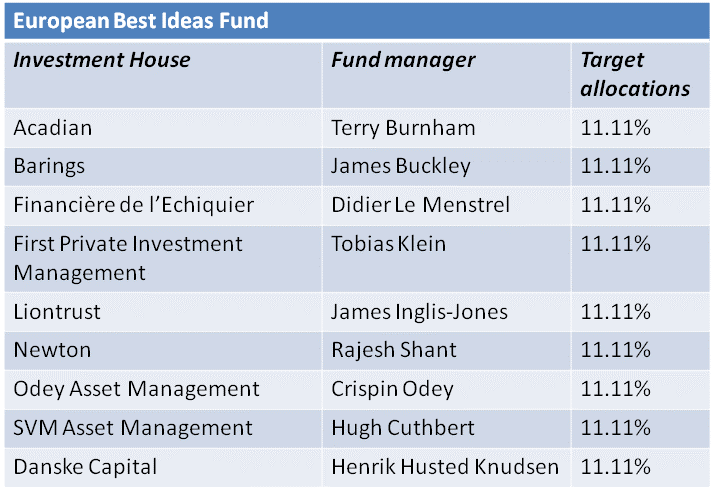
There are a number of hedge fund managers and managers of absolute return funds amongst the roster of managers employed by Skandia in the Best Ideas Funds. In fact I would go so far as to say that there is a disproportionate number of such managers amongst the portfolio managers used (see tables below). Would that be because hedge fund managers tend to apply the best portfolio management practices given by Skandia more than long-only managers?



Friday, 19 February 2010

From the GLG Earnings Release - Flows, High Water Marks and the Outlook for CB Arbitrage

From the Full Year Statements for GLG Partners Inc.

Noam Gottesman, Chairman and Co-CEO of GLG said : “Encouragingly, AUM flows at GLG have turned definitively positive over the past six months and looking forward, I am confident that GLG remains well-positioned to be a leading beneficiary as industry flows expand."

4Q net inflows of $723 million, mostly reflecting interest in GLG's alternative strategy managed accounts,. Net inflows in the 3Q (across long only and hedge) were $216m.


Conference Call Extracts on Flows, High Water Marks and the Outlook for CB Arbitrage


Noam Gottesman
“In fact, we are seeing growing interest in GLG from both existing and potential clients. Our organic net flows were positive again in the fourth quarter, after turning positive in the third quarter, following six months of stabilizing trends. Importantly, the redemption wave that crested late in 2008 now appears well behind us.

"Further, though the pacing and scale of this next cycle of inflows remain difficult to forecast, we believe it has definitely begun. It is notable that we gained several significant new client relationships in the quarter, including among others, a prominent sovereign wealth fund and a European Insurance company.

"At the end of the fourth quarter we had approximately $7.5 billion in AUM above water within 5% of high watermark, part of a potential 12.5 billion in performance fee eligible assets under management. We have another 0.8 billion in AUM within five to 10% of the respective high watermark.

"I'm strongly encouraged by the flows we have seen during the second half of 2009 and in the early weeks of 2010."


Jeff Rojek, CFO

At the end of December, we had roughly 7.5 billion out of a possible 12.5 billion of performance fee eligible AUM, above or within 5% of their respective high watermarks. These numbers include AUM, special asset vehicles and other liquidating strategies.

Broken down by strategy, approximately 3.2 billion of our alternative AUM, 0.9 billion of our long-only AUM, and 1.7 billion of our 130/30 strategies or similar AUM is above water. Also, approximately, 0.4 billion of our alternative AUM, 0.2 billion of our long-only AUM, and 1.1 billion of our 130/30 strategies or similar AUM is within 5% or less of their respective high watermarks.

Of the remaining five billion of AUM under water, 1.8 billion is in alternative strategies and 3.2 billion is in our long-only strategy. Briefly again even further 0.4 billion of alternative AUM and 0.4 billion of long-only AUM is between five and 10% of their respective high water marks. 0.8 billion of alternative AUM and 1.7 billion of long-only AUM between ten and 30% of their high water marks. While 0.7 billion of alternative AUM and as 1 billion of long-only AUM is more than 30% below the high water marks.


Q&As


(A - Noam Gottesman, Chairman and Co-Chief Executive Officer): We're very encouraged by what we're seeing in the pipeline. The inflow cycle as we mentioned, it's hard to sort of guage the pacing, the magnitude but we're actually seeing it pretty much across the board, definitely seeing a lot of alternative interest now, and whereas in the previous few months, there were some alternative but mainly traditional. But we are - we're seeing very strong flows into the Long-Short products, we're seeing strong flows into emerging market. And convertible, we're seeing very good interest in the UCITS III product,

...A large part of the 4Q flows were from sovereign investors in long only mandates.


A - Noam Gottesman, Chairman and Co-Chief Executive Officer): Yes, generally, I think, people are definitely allocating. There is no question. There is certainly an awful lot of interest, and I think they're not doing it because they're bored. I think they've got money to put to work, and alternatives definitely delivered. And I think the prospects are looking bright for the industry right now.


(Q - Roger Freeman): Are you finding that you're coming in as a result of manager substitution or are you coming in as an additional manager?

(A - Noam Gottesman, Chairman and Co-Chief Executive Officer): I think it's both. I think the people sat on their hands for much of last year. They redeemed in some places, but they sat on their hands. They're just - I'm not really seeing - it's hard for me to gauge where it's coming from, but it's definitely coming.

… The alternative assets continued to be at full alternative fees, we are not seeing any real pricing pressure there.


(Q - Roger Freeman): What are your thoughts on the convert market outlook? I think, you mentioned there was strong interest in the fourth quarter. Issuance seems to have been light so far this year relative to what people were expecting. Do you see a lot of issuance coming down the pike, and is that a key to driving returns and flows in that area?

(A - Noam Gottesman, Chairman and Co-Chief Executive Officer): I think we're still very positive on the convertible market and we were for - we have been, as you know. And it’s a market that's done exceptionally well. Our convertible funds - our convertible arbitrage funds - have continued to perform very strongly, including in January where the convertible arbitrage fund, I think, was up close to 9%.

We think issuance will continue. And we think that new deals are going to have to come cheap, and I think it's going to provide opportunities. And the volatility in the market should be very beneficial. So we do continue to feel strongly positive on it. We also believe that there would be a large M&A flow that continues, which will also drive new issuance.

GLG Global Convertible Fund versus Bloomberg Active Convertible Index

Wednesday, 2 December 2009

Podcast 2- A Discussion with UK Equity Portfolio Manager Nick Shenton at Polar Capital

Click on the links to download or play the sound files (embedded player available).

Part 1 (7 minutes 51 seconds)

0.30 Joining Phil Hardy at Polar Capital

1.50 Idea generation

4.40 What Phil Hardy brings to the process of stock selection

5.15 Harder to find shorts now

6.30 Shorts can work faster than longs


Part 2 (10 minutes 50 seconds)

0.25 Websites look at daily

1.35 Websites useful for company insight

2.58 Segro as an example

4.50 Recent investment book reading- Niall Ferguson, "The Greatest Trade Ever"

8.37 Risk/Reward for UK equity trades

9.05 Two other influential books - "Soros on Soros" and "Inside the House of Money"


With thanks to Nick Shenton CFA who works on UK equity hedge fund and absolute return products with Polar Capital Director Philip Hardy


The Greatest Trade Ever

By Gregory Zuckerman
Reviewed by Alexandra Scaggs from www.smartmoney.com

Ever wonder how a single trade can create a legend? Gregory Zuckerman outlines how just such a thing happened with John Paulson and the rest of the characters who profited wildly from the collapse of the real estate bubble."

In The Greatest Trade Ever," Zuckerman, who writes The Wall Street Journal’s "Heard on the Street" column, focuses as much on the personalities and characters of the investors as on the bubble and collapse that increased their wealth exponentially.

Players here include Paulson, whom Zuckerman characterizes as a reformed playboy and true skeptic; Paolo Pellegrini, a Wall Street outsider who went to Paulson for his last shot at a career; Jeffrey Greene, the Hollywood version of a big-shot investor; and Andrew Lahde, the young West-Coast investor who cashed out and left finance for good.

The book addresses how deals are made and how personality counts just as much as the financial mechanics behind the trade, which may be why Paulson has come out with a statement saying he is “disappointed” with the book. But Zuckerman shows that in finance, office politics can matter as much as smarts.

Monday, 9 November 2009

A difference between long only and hedge - Schroders for example

At a series of presentations by senior Schroders executives recently one of the differences between long-only and hedge fund management came through forcibly. Gary Clarke, Head of European Equities, gave a good pitch about how well they had done in the last couple of years. And indeed the Schroders ISF European Equity Alpha Fund is first quartile amongst the European equity funds domiciled in Luxembourg universe, according to Micropal.

The Fund is ahead of the index by about 10% in the last year or so. So Schroders have done a very good job on the European equity side versus the competition by weighting the sectors appropriately in the last couple of years.Gary Clarke said such good differential performance was achieved whilst “of course, we were fully invested.”

That was the shock statement to me. I’ve been in the hedge fund world for so long that that casual conditionality thrown out by a long-only manager that he is structurally fully-invested came as an icy blast of wind in my face. The fund balance sheets are Long 100 Short 0.

At this point it seemed a very artificial, not to say limiting structure. Of course, there are advantages in staying long-only. My old boss at Clerical Medical, Robert Walther, whom I admired enormously, used to say that portfolio managers couldn’t time markets. In his mind they were better off concentrating on picking sector and stocks and letting him allocate between asset classes and geographies. Given his talents he was probably right in that case. Schroders are following a pattern set in the 1980’s and which I had thought, in my naivety, had disappeared ten years ago.


For quite a few years into their hedge fund management expansion Gartmore used to run hedge funds which followed the template of Alphagen Capella. So the funds had a limited net exposure to markets – this makes the return stream driven off alpha much more than market beta. With this structure the hedge fund managers don't have to have a distinctive talent to time markets. Amongst Gartmore’s hedge funds that have been successful recently are hedge funds that utilised a wider band of net exposures, including running net short last year. Gartmore has moved on.


It struck me listening to Schroders presentations that they have some good equity selection alpha. They could at least run limited net hedge funds to start with. Schroders have a fine fund of hedge funds operation in NewFinance. They have a credit hedge fund that is in its ninth year and manages $106m. Schroders recently announced that they are launching a regulated, transparently operated platform for UCITS III funds designed to give investors easier access to hedge fund expertise. The first Fund available on the platform is exposure to European hedge fund pioneer John Armitage’s Egerton. Egerton Capital has a good performance record, however Schroders as a business would be much better off developing its own single manager hedge fund products.


p.s. If you want help in doing this, Alan Brown (Schroders CIO), give me a call – that is the kind of project my consultancy Enhance Consulting gets involved in.